
Escolha um formato:
| zip | Baixar grátis |
|---|---|
| rar | Baixar grátis |
| epub | Baixar grátis |
| Baixar grátis | |
| lit | Baixar grátis |
| odf | Baixar grátis |
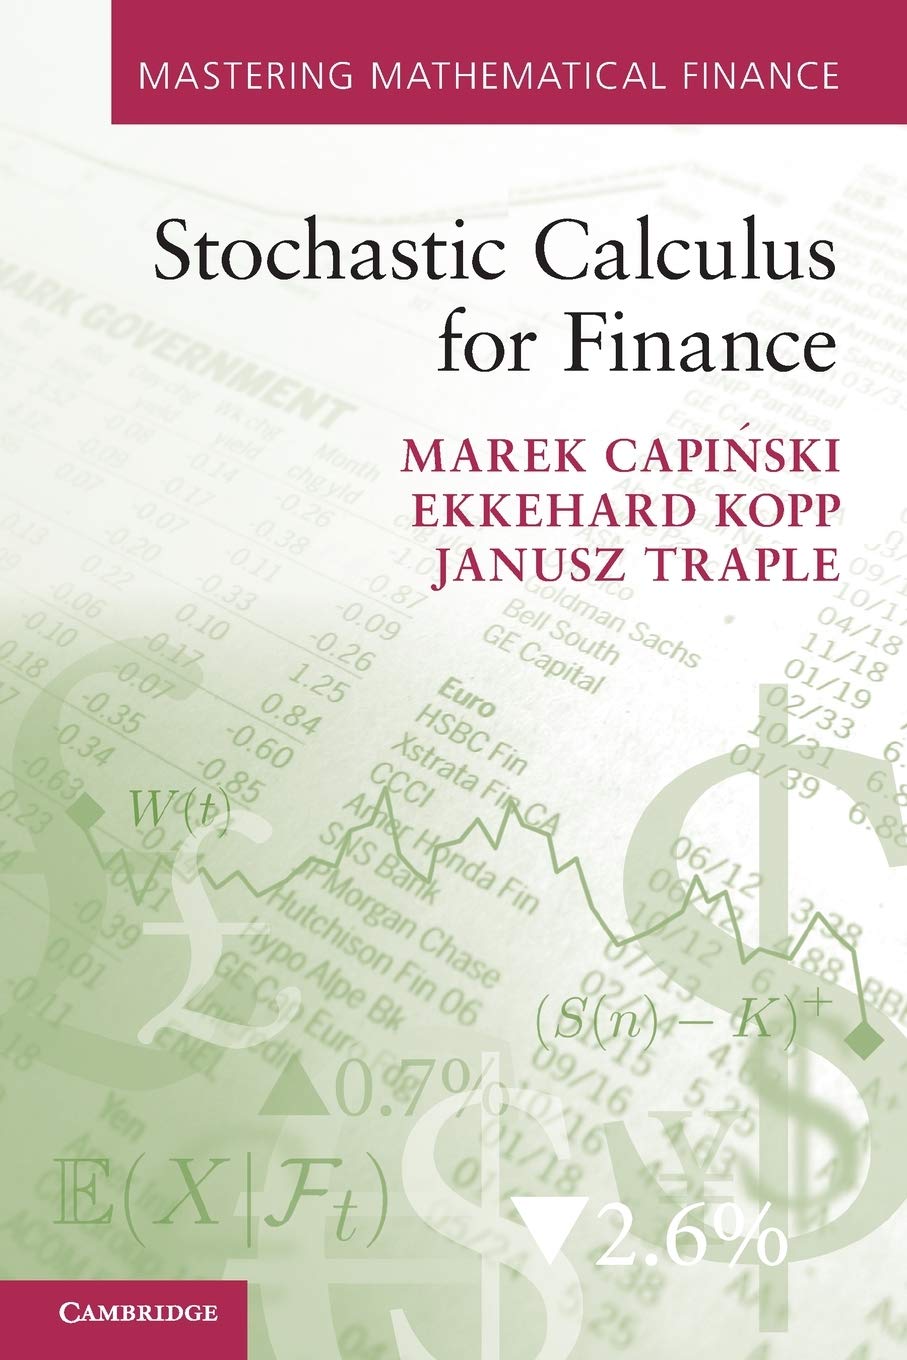
Descrição do livro
This book focuses specifically on the key results in stochastic processes that have become essential for finance practitioners to understand. The authors study the Wiener process and Itô integrals in some detail, with a focus on results needed for the Black-Scholes option pricing model. After developing the required martingale properties of this process, the construction of the integral and the Itô formula (proved in detail) become the centrepiece, both for theory and applications, and to provide concrete examples of stochastic differential equations used in finance. Finally, proofs of the existence, uniqueness and the Markov property of solutions of (general) stochastic equations complete the book. Using careful exposition and detailed proofs, this book is a far more accessible introduction to Itô calculus than most texts. Students, practitioners and researchers will benefit from its rigorous, but unfussy, approach to technical issues. Solutions to the exercises are available online.
Autores populares
Icon Group International (402) Publishing lmgdaw (341) Nikolay Krechet (266) Unknown Author (197) Lyudmil Tsvetkov (179) Barrett Williams (166) Kennie B Journals (158) Riddler Books (122) ChatGPT ChatGPT (118) NAK Legal Publishing (116) Evgeniia Naumchenko (114) Sharifa McFarlane (97) Jillo Trukudo (96) Quick Witted Coconut (94) Roggie Clark (94) Mint and Cherry Notebooks (93) Marina Buchholz B.Eng (89) Iwona Makara (87) Mary Hirose (87) Kingston Publishing (85)