
Escolha um formato:
| zip | Baixar grátis |
|---|---|
| rar | Baixar grátis |
| epub | Baixar grátis |
| Baixar grátis | |
| lit | Baixar grátis |
| odf | Baixar grátis |
Descrição do livro
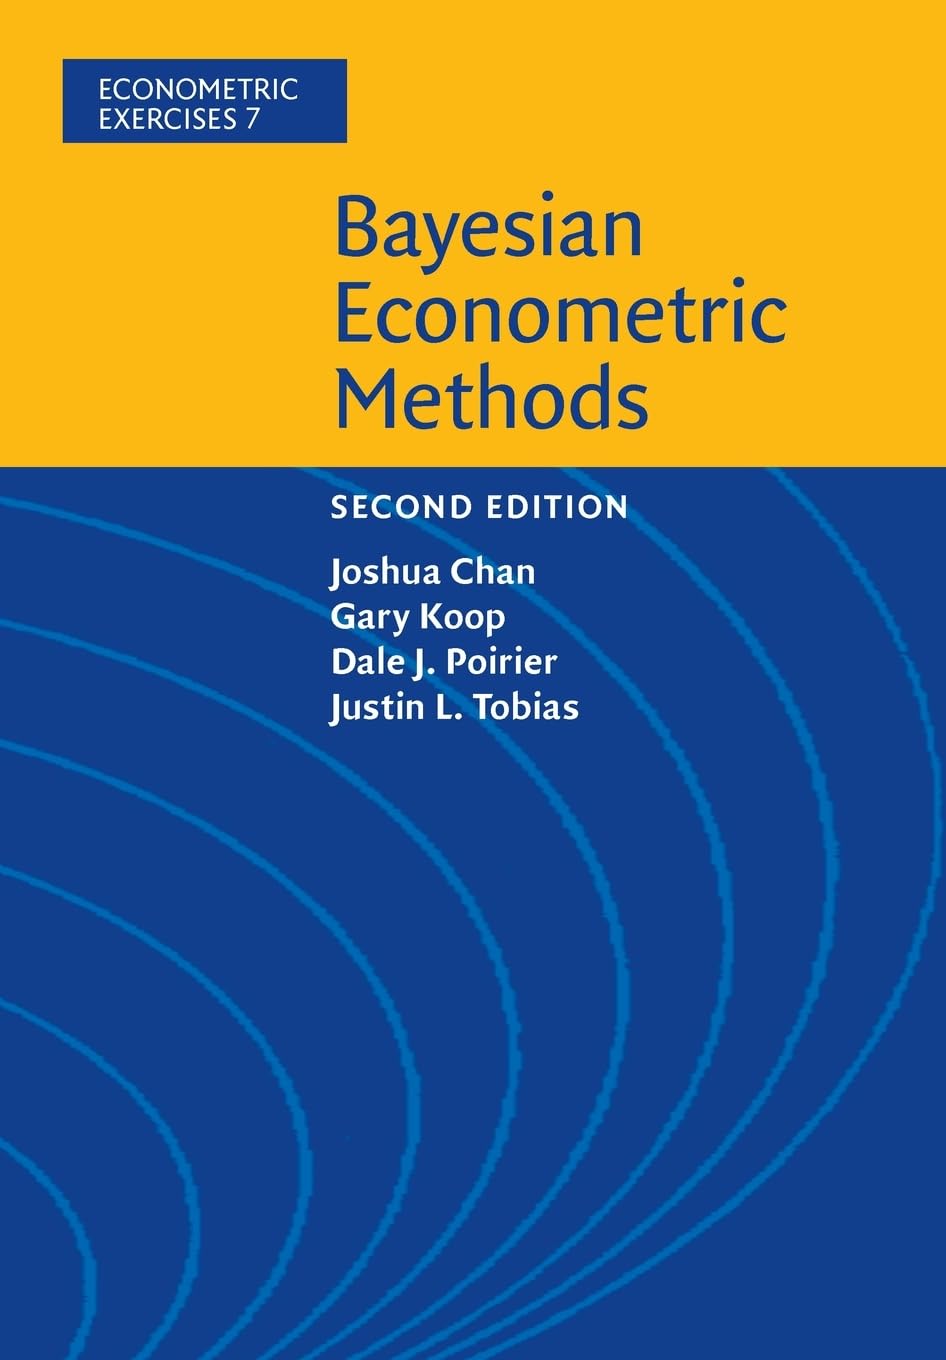
Bayesian Econometric Methods examines principles of Bayesian inference by posing a series of theoretical and applied questions and providing detailed solutions to those questions. This second edition adds extensive coverage of models popular in finance and macroeconomics, including state space and unobserved components models, stochastic volatility models, ARCH, GARCH, and vector autoregressive models. The authors have also added many new exercises related to Gibbs sampling and Markov Chain Monte Carlo (MCMC) methods. The text includes regression-based and hierarchical specifications, models based upon latent variable representations, and mixture and time series specifications. MCMC methods are discussed and illustrated in detail - from introductory applications to those at the current research frontier - and MATLAB(R) computer programs are provided on the website accompanying the text. Suitable for graduate study in economics, the text should also be of interest to students studying statistics, finance, marketing, and agricultural economics.

Autores populares
Icon Group International (402) Publishing lmgdaw (341) Nikolay Krechet (266) Unknown Author (197) Lyudmil Tsvetkov (179) Barrett Williams (166) Kennie B Journals (158) Riddler Books (122) ChatGPT ChatGPT (118) NAK Legal Publishing (116) Evgeniia Naumchenko (114) Sharifa McFarlane (97) Jillo Trukudo (96) Quick Witted Coconut (94) Roggie Clark (94) Mint and Cherry Notebooks (93) Marina Buchholz B.Eng (89) Iwona Makara (87) Mary Hirose (87) Kingston Publishing (85)