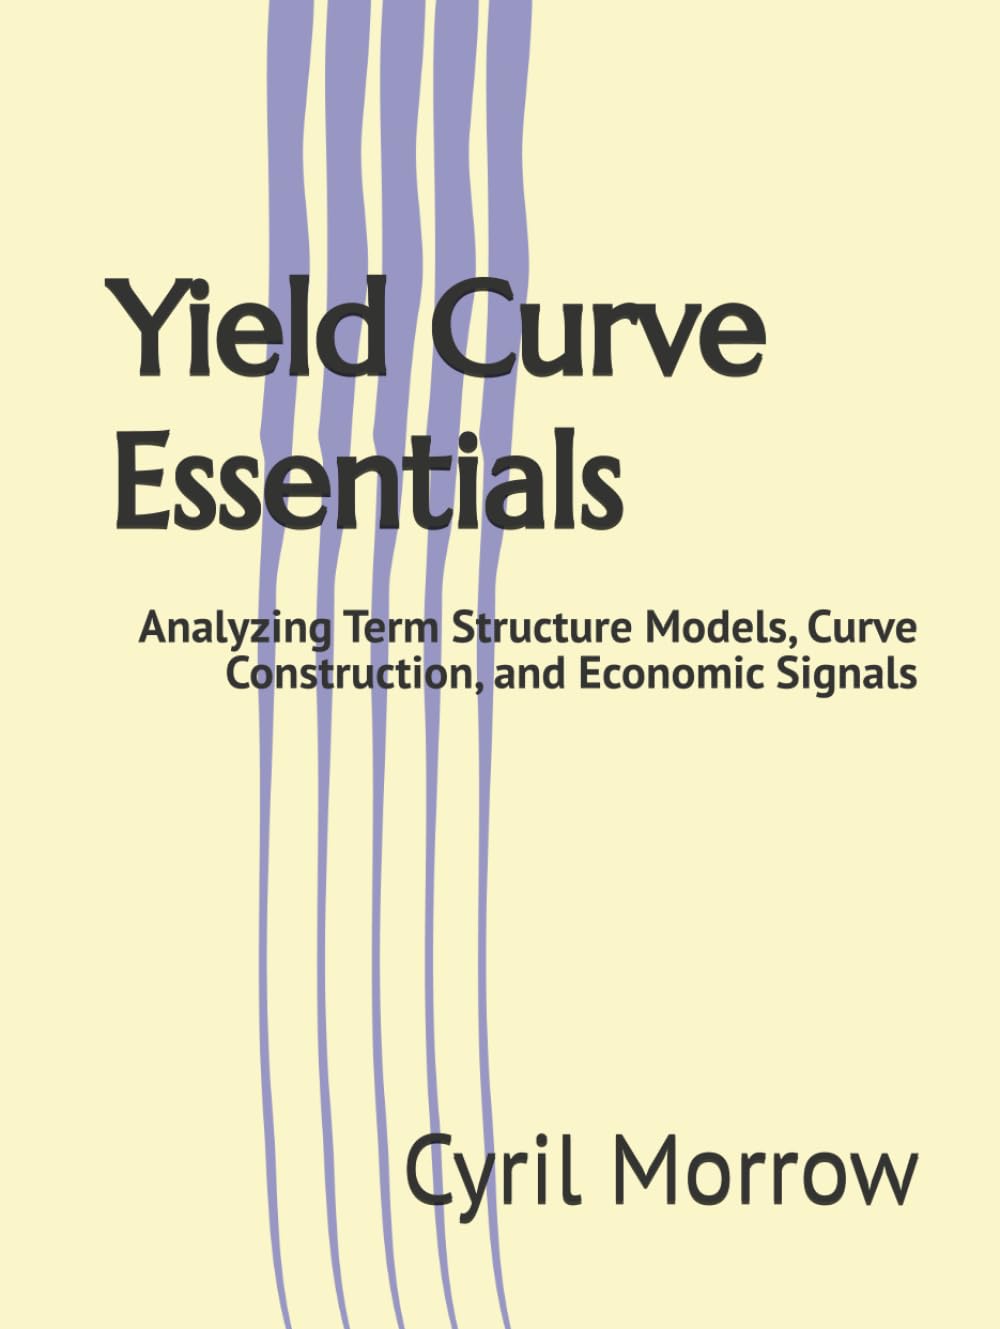
Yield Curve Essentials: Analyzing Term Structure Models, Curve Construction, and Economic Signals baixar livro de graça
por Cyril Morrow
Escolha um formato:
| zip | Baixar grátis |
|---|---|
| rar | Baixar grátis |
| epub | Baixar grátis |
| Baixar grátis | |
| lit | Baixar grátis |
| odf | Baixar grátis |
Yield Curve Essentials: Analyzing Term Structure Models, Curve Construction, and Economic Signals
Clear, practical, and technically grounded, this book explains how yield curves are built, interpreted, and used in real financial work. It moves from first principles to implementation, showing how rates, tenors, discounting, and no-arbitrage conditions fit together before advancing into bootstrapping, interpolation, smoothing, and validation. Readers get a full view of the curve-building process across multiple market settings, including government bonds, swaps, bills, futures-linked instruments, and multi-curve frameworks. The text also pays close attention to data preparation, quote conventions, accrued interest, and the common pitfalls that can distort curve construction. The final chapters bring everything together in a practical workflow, from raw market quotes to reproducible analytics and risk reports. Along the way, the book emphasizes clean implementation, transparent assumptions, and results that can be checked against market instruments. Ideal for quants, fixed-income analysts, risk professionals, and advanced students who want a rigorous guide to yield curve methods without losing sight of real-world usage.
Procurando Yield Curve Essentials: Analyzing Term Structure Models, Curve Construction, and Economic Signals? Aqui você encontra tudo sobre este livro de Cyril Morrow em 22 de julho de 2026. Nesta página estão a descrição da obra, os detalhes da edição (225 páginas) e os formatos disponíveis para baixar: epub, pdf, lit, odf. O livro está escrito em Inglês. Se você gosta de Livros Internacionais, Administração, Negócios e Economia, Finanças, Juros, explore também outros títulos da mesma categoria no Leitura em português. Veja ainda as outras obras de Cyril Morrow em nosso catálogo.
Autores populares
Icon Group International (402) Publishing lmgdaw (341) Nikolay Krechet (266) Unknown Author (197) Lyudmil Tsvetkov (179) Barrett Williams (166) Kennie B Journals (158) Riddler Books (122) ChatGPT ChatGPT (118) NAK Legal Publishing (116) Evgeniia Naumchenko (114) Sharifa McFarlane (97) Jillo Trukudo (96) Quick Witted Coconut (94) Roggie Clark (94) Mint and Cherry Notebooks (93) Marina Buchholz B.Eng (89) Iwona Makara (87) Mary Hirose (87) Kingston Publishing (85)Idiomas populares
Inglês Espanhol Alemão Francês Italiano Português Japonês Polonês Holandês Sueco Russo Árabe Chinês Hebraico Multilíngue Catalão Tradicional chinês Espanhol, Inglês Alemão, Inglês Ucraniano