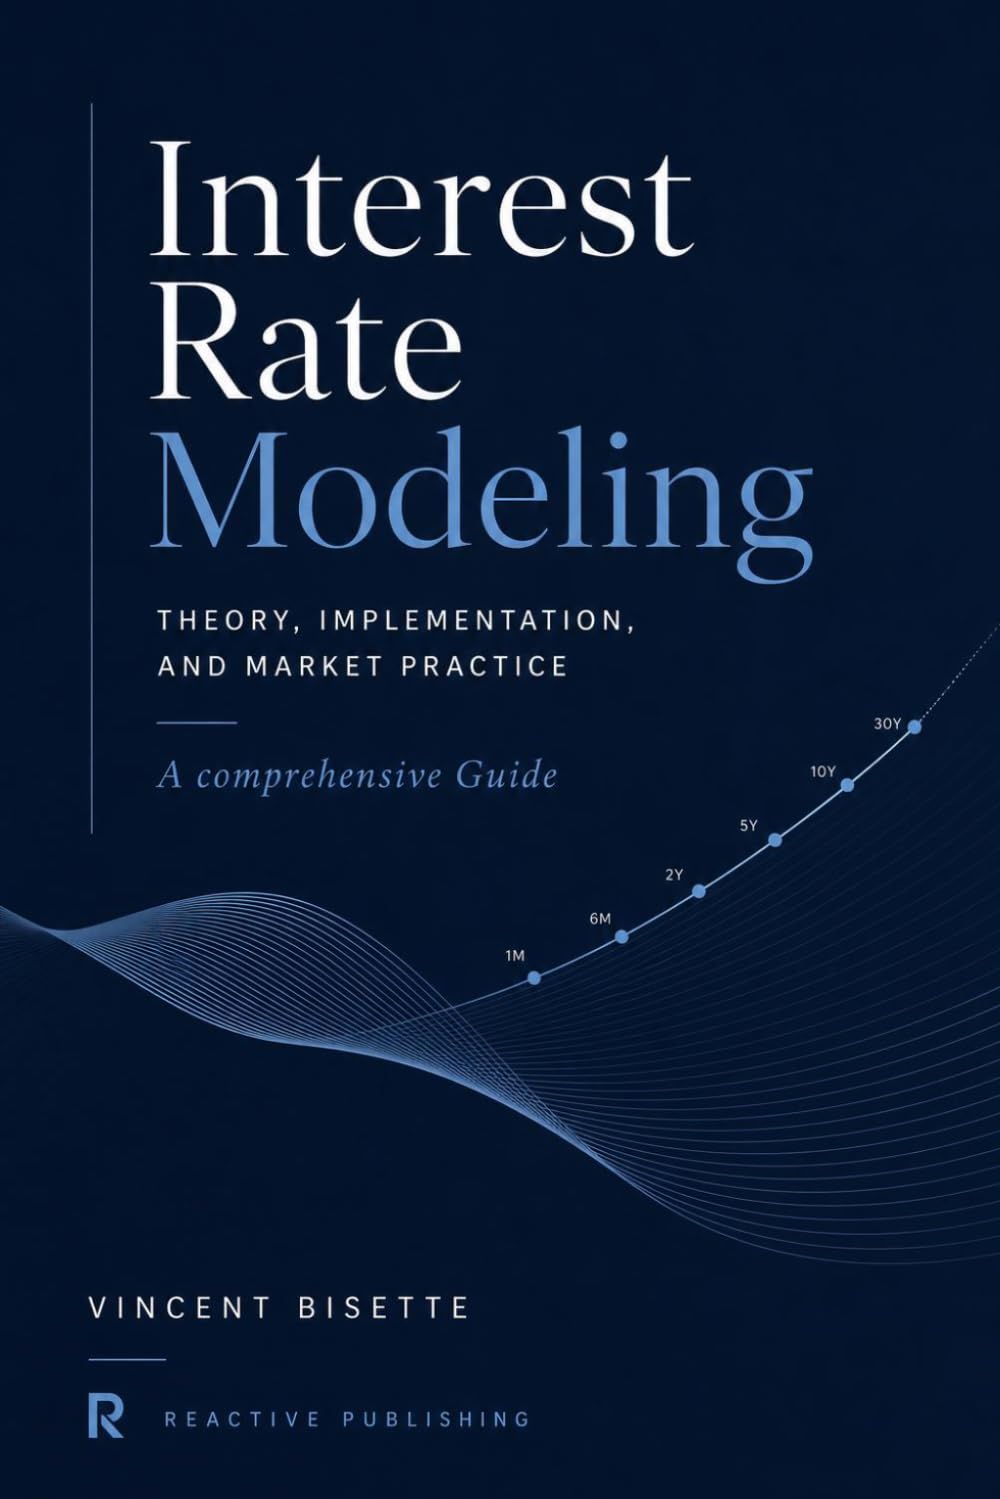
Interest Rate Modeling: Theory, Implementation, and Market Practice baixar livro de graça
por James Preston
Escolha um formato:
| zip | Baixar grátis |
|---|---|
| rar | Baixar grátis |
| epub | Baixar grátis |
| Baixar grátis | |
| lit | Baixar grátis |
| odf | Baixar grátis |
Interest Rate Modeling: Theory, Implementation, and Market Practice
Reactive Publishing Interest Rate Modeling: Theory, Implementation, and Market Practice by Vincent Bisette offers a comprehensive, practitioner-oriented guide to one of the most technically demanding areas of quantitative finance. This book bridges the gap between academic theory and real-world trading floors, delivering a clear and accessible treatment of interest rate models, from foundational short-rate models (such as Vasicek and Hull-White) to advanced frameworks including multi-factor affine models, the LIBOR Market Model (LMM), SABR, and modern stochastic volatility approaches. Written in Bisette's signature hands-on style, blending mathematical precision with code examples, case studies, and market anecdotes-this book is ideal for: Whether you're building models from scratch, refining existing systems, or deepening your understanding of how interest rates drive global markets, Interest Rate Modeling equips you with the tools and intuition needed to navigate this complex domain with confidence. It stands as an essential resource for anyone serious about mastering the theory, code, and commercial realities of interest rate derivatives.
Procurando Interest Rate Modeling: Theory, Implementation, and Market Practice? Aqui você encontra tudo sobre este livro de James Preston em 1 de julho de 2026. Nesta página estão a descrição da obra, os detalhes da edição (356 páginas) e os formatos disponíveis para baixar: epub, pdf, lit, odf. O livro está escrito em Inglês. Se você gosta de Livros Internacionais, Computação, Informática e Mídias Digitais, Programação, Python, explore também outros títulos da mesma categoria no Leitura em português. Veja ainda as outras obras de James Preston em nosso catálogo.
Autores populares
Icon Group International (402) Publishing lmgdaw (341) Nikolay Krechet (266) Unknown Author (197) Lyudmil Tsvetkov (179) Barrett Williams (166) Kennie B Journals (158) Riddler Books (122) ChatGPT ChatGPT (118) NAK Legal Publishing (116) Evgeniia Naumchenko (114) Sharifa McFarlane (97) Jillo Trukudo (96) Quick Witted Coconut (94) Roggie Clark (94) Mint and Cherry Notebooks (93) Marina Buchholz B.Eng (89) Iwona Makara (87) Mary Hirose (87) Kingston Publishing (85)Idiomas populares
Inglês Espanhol Alemão Português Francês Italiano Japonês Polonês Holandês Sueco Russo Chinês Hebraico Multilíngue Catalão Tradicional chinês Espanhol, Inglês Português, Português Alemão, Inglês Ucraniano